Key Takeaways:
- What is an MIB report? A consumer file containing certain medical and underwriting information reported during previous insurance applications.
- What is a Milliman IntelliScript report? A report containing available prescription drug histories, medical claims, diagnosis codes, and procedure information.
- Why should physicians check both reports? Each service collects different information that may influence life insurance and disability insurance underwriting.
- Can inaccurate medical records affect insurance approval? Yes. Incorrect diagnoses, prescription histories, or billing codes may cause delays, additional questions, or unfavorable underwriting decisions.
- Can physicians dispute incorrect information? Yes. Both services provide procedures for requesting reviews of inaccurate information.
Should Physicians Order an MIB Report and a Milliman Report Before Applying for Disability or Life Insurance?
Before applying for life insurance or disability insurance, physicians should review the medical information insurers may use during underwriting.
In this episode of The Responsible Resident, Amber Stitt explains the differences between MIB reports and Milliman IntelliScript reports, how prescription histories and medical billing codes can affect insurance eligibility, and why correcting inaccurate health information before applying for coverage is an important first step.
What Is an MIB Report and How Does It Affect Life Insurance Underwriting?
MIB, formerly known as the Medical Information Bureau, maintains information reported by participating insurance companies during previous applications.
When physicians apply for individual life insurance or disability insurance, participating insurers may use MIB information to compare previous disclosures with current application answers.
For example, a medical condition disclosed during an earlier application may appear in an MIB Consumer File.
However, MIB information alone cannot determine an underwriting decision without further investigation.
What Is Milliman IntelliScript and What Medical Information Does It Collect?
Milliman provides electronic health information used in insurance underwriting, including available prescription histories and medical claims.
Unlike MIB, which primarily reflects information reported during previous insurance applications, Milliman may contain pharmacy records, diagnosis codes, and medical procedures.
These records can raise questions about an applicant’s health history.
For physicians seeking specialty-specific disability insurance, understanding what appears in these reports can help prepare for medical underwriting.
How Can Incorrect Medical Billing Codes Affect Insurance Eligibility?
Medical billing codes do not always represent confirmed diagnoses.
For example, a physician may receive testing to rule out a condition, but the associated diagnosis code could appear in medical claims data.
Similarly, medications may be prescribed for multiple conditions, potentially leading underwriters to request clarification.
Incorrect or incomplete information can create unnecessary complications during life insurance or disability insurance underwriting.
Why Should Physicians Review Both MIB and Milliman Reports?
MIB and Milliman collect different information from different sources.
Reviewing both reports helps physicians identify potential discrepancies before applying for insurance.
This is especially important for medical residents, fellows, and attending physicians seeking individual disability insurance or life insurance coverage.
Although reviewing reports cannot guarantee approval or preferred underwriting rates, it allows applicants to address legitimate inaccuracies proactively.
How Can Physicians Request and Correct Their Insurance Medical Reports?
Physicians can request their MIB Consumer File through MIB.com and their Milliman IntelliScript report through RxHistories.com.
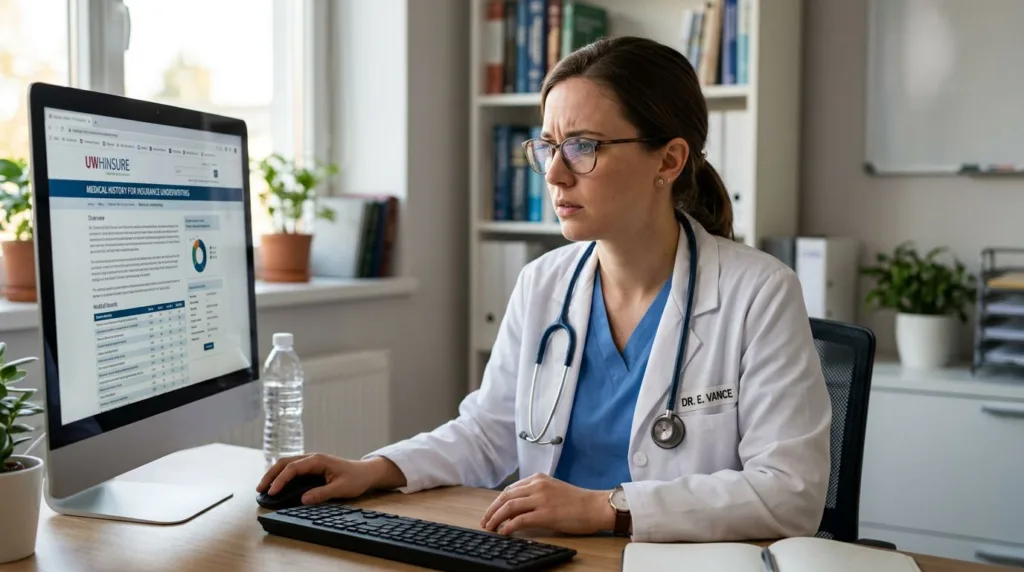
After receiving the reports, review medical diagnoses, prescription histories, and other available information for accuracy.
If discrepancies appear, contact the reporting organization to initiate its dispute process.
Supporting physician documentation or medical records may help clarify inaccurate information.
Correcting a consumer report does not automatically correct the original medical record, so additional follow-up may be necessary.
From Amber’s Desk
Before applying for life insurance or specialty-specific disability insurance, request both reports, review the information, and address legitimate errors whenever possible.
Understanding your medical underwriting history helps you approach insurance applications with greater preparation and confidence.
You don’t need to make a decision today, but you do need to understand your options.
Clarity creates confidence.
To take the next step and build a strategy that supports your career and financial future, download the FREE Medical Professionals Blueprint here.
About Amber Stitt
Amber Stitt is a nationally recognized Disability Insurance specialist with over 15 years of experience helping physicians and high-income professionals protect their income and financial stability.
As co-owner of MD Disability Quotes with top Disability Expert, Scott Nelson-Archer, and founder of Stitt Strategies, Amber works with physicians nationwide to design income protection strategies that are personal, portable, and aligned with the realities of a specialized medical career.
She is also the host of The Responsible Resident, an education-first podcast focused on helping medical trainees understand how financial decisions, especially around income protection and underwriting, can shape their long-term options.
Her work centers on helping physicians make informed decisions before limitations appear, so they can protect their income, preserve flexibility, and move forward with confidence.
If you would like to schedule a disability insurance strategy session, click here.
If you would like to request physician disability insurance quotes, click here.
You can email us: info@amberstitt.com
Call 480-707-2771 (9 AM-5 PM MST)
Text “Insurance” to 480-707-2771 at your convenience.
Request Your MIB and Milliman Reports:
Contact MIB: Request Your MIB Consumer File or call (866) 692-6901.
Order Your Milliman Report: Milliman IntelliScript Consumer Report or call (877) 211-4816.